The documents are in order, the registry extract is clean, the references check out and the lawyer has no objections. And yet the deal depends on several things that exist only as statements: that the key client relationship is not about to end, that there is no second buyer in the background, that the founder is not quietly building the same product elsewhere, that the inventory in the warehouse belongs to the company. Due diligence verifies what is recorded. The gap it leaves is what was said out loud.
The claims that documents cannot confirm
- Undisclosed agreements. Additional agreements, verbal arrangements regarding discounts, and commissions received personally.
- Stability of the customer base. Has a major client indicated their intention to terminate the business relationship?
- Concurrent activities. A rival company registered in the name of a relative or a former colleague.
- Ownership of assets. Stock, equipment or software belonging to another person.
- Known liabilities. A lawsuit currently being prepared, an audit by the regulatory authority, and outstanding debt to a supplier.
- Reason for sale. Which almost never matches the one mentioned at the first meeting.
Turning a concern into a testable statement
| Can be verified | Cannot be verified |
|---|---|
| Is there a separate agreement with a specific supplier? | Is a business a sound investment? |
| Did the client give notice of the termination of the business relationship by the specified date? | Will income levels remain the same next year? |
| Does the seller hold a stake in a competing company? | Does competition pose a risk? |
| Were any payments received personally, outside the accounts? | Were the management decisions well-founded? |
| Was the dispute or claim concealed? | Is the other side acting honourably? |
Opinions, predictions and personal characteristics fall entirely outside the scope of this method. What remains is a narrow but practically useful area: specific, date-bound statements that can be verified, which the counterparty has already put forward and which no register is able to confirm.
Why it is offered, not imposed
An examination is voluntary by definition, and in a transaction that is a feature rather than a limitation. Proposing that both sides answer the same short list of questions is itself a negotiating position: it is usually accepted when the claims are solid and declined with elaborate reasons when they are not. Where both parties agree, the exercise narrows the contested ground quickly and lets the lawyers draft warranties around what is actually in dispute.An examination is voluntary by definition, and in a transaction that is a feature rather than a limitation. Proposing that both sides answer the same short list of questions is itself a negotiating position: it is usually accepted when the claims are solid and declined with elaborate reasons when they are not. Where both parties agree, the exercise narrows the contested ground quickly and lets the lawyers draft warranties around what is actually in dispute.It is worth being precise about weight. German courts have held polygraph findings unsuitable as evidence in criminal proceedings, and no court is obliged to take such a report into account. The value of the document is commercial rather than forensic: it informs a decision before signature, supports the wording of warranties and indemnities, and occasionally ends a negotiation that should have ended earlier.
It is important to have a clear understanding of the evidential value of the results. German courts have ruled that polygraph test results are inadmissible as evidence in criminal proceedings, and no court is obliged to take such findings into account. The value of the document is commercial rather than forensic: it helps in making decisions prior to signing an agreement, formulating guarantees and provisions regarding compensation for losses, and sometimes even in terminating negotiations that should have been concluded earlier.
How a session is structured
- Consultation. The statements are analysed and a single theme is identified; a wide range of issues is divided amongst the individual sessions.
- Written consent clearly stating the topic and the questions that are excluded from the assessment.
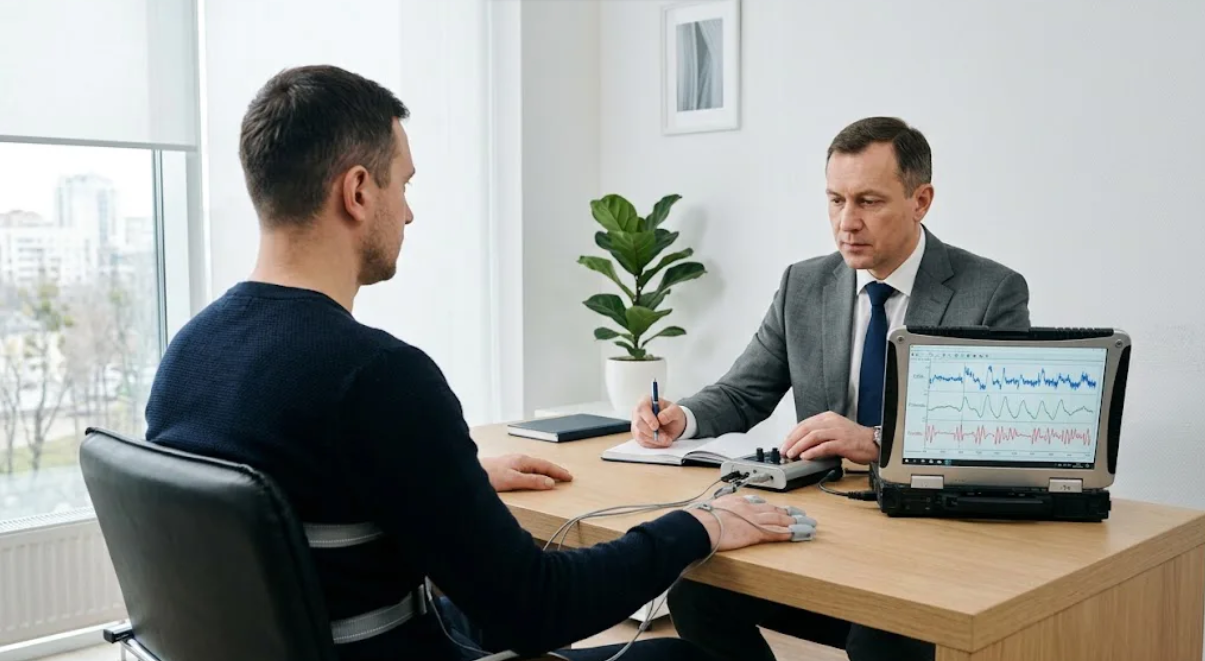
- A pre-test interview lasting about half an hour. The wording of each question is agreed upon line by line before the recording of the figures begins.
- Recording of readings over a period of 40–60 minutes, during which a set of questions is repeated several times, with the order of the questions changing.
- Result is provided on the same day, together with an official written opinion if the matter requires further consideration.
A remote format is available for the preparatory stages, which is important when the parties and their advisers are based in different countries. Certified specialists work in English, and industry experts estimate the accuracy of a properly conducted audit at 95–98 per cent. As a due diligence review under an agreement almost always covers several areas, the cost is calculated according to the specific scope of work rather than on a fixed-price basis. The price for each corporate engagement is determined on a case-by-case basis following an initial free consultation.
At what stage of the transaction should the audit be carried out?
The optimal time frame is quite narrow. If the review is carried out too early, there will not yet be any specific claims that can be verified, as they have not yet been formulated in detail. If it is carried out too late, the commercial terms will already have been agreed, so an unfavourable response will create a problem rather than helping to reach a decision. The most practical time is after the initial document review stage and before the main terms of the agreement are signed, when the seller has already made specific representations and is still keen to complete the transaction.
One rule regarding the sequence of actions helps to save money: first, set out the representations in writing. A questionnaire covering warranties, client relationships, connected persons and obligations fulfils two purposes at once. It provides lawyers with a contractual framework and sets out precisely those specific, date-bound statements that can be verified. Without this, the subject matter has to be determined directly whilst preparing for the session, and overly broad topics yield poor results.
When it is best to dispense with checks altogether
- The doubt concerns the interpretation of a provision of the contract, not any hidden actions.
- The discrepancy is already apparent in the accounts, so the auditor will be able to sort it out more quickly.
- The other party refuses to discuss the matter at all, as an audit cannot be carried out without their consent.
- The value of the transaction is close to the total costs of consultancy and due diligence.
- The decision has already been taken; the check is merely a formality.
For a buyer putting the verification plan together, the published service range is the place to start: the corporate formats, examiner credentials and booking process behind a Polygraph test Germany are described openly, which makes it straightforward to brief lawyers and advisers on what the step does and does not involve.
Can employees of the target company be examined
Only voluntarily, and only on topics connected to their work. In practice the people with the relevant knowledge are often the finance lead or the sales director, and their participation is arranged through the seller rather than around them.
How long does preparation take
Usually a few days once the written statements exist. Collecting the claims is the slow part; the session itself is a single appointment, and the verbal outcome follows the same day.
Should the report be shared with the other side
That is agreed before the session, not after. Where both parties take part, mutual disclosure is the norm and makes the exercise worth doing; where one side commissions it alone, the document belongs to that client and is usually kept for internal decision making.